Wednesday, October 21, 2026

12:37 PM

Right to Repair Laws: Who Owes You Parts

You ask the maker for a replacement screen. The reply is that parts go only to authorized shops, and the shop quotes a price that makes the old phone look like the better buy. Whether that refusal is lawful depends on the state you live in and the date your device was first sold. A right to repair law is the rule that settles it, and in 2026 the answer changes from one state to the next.
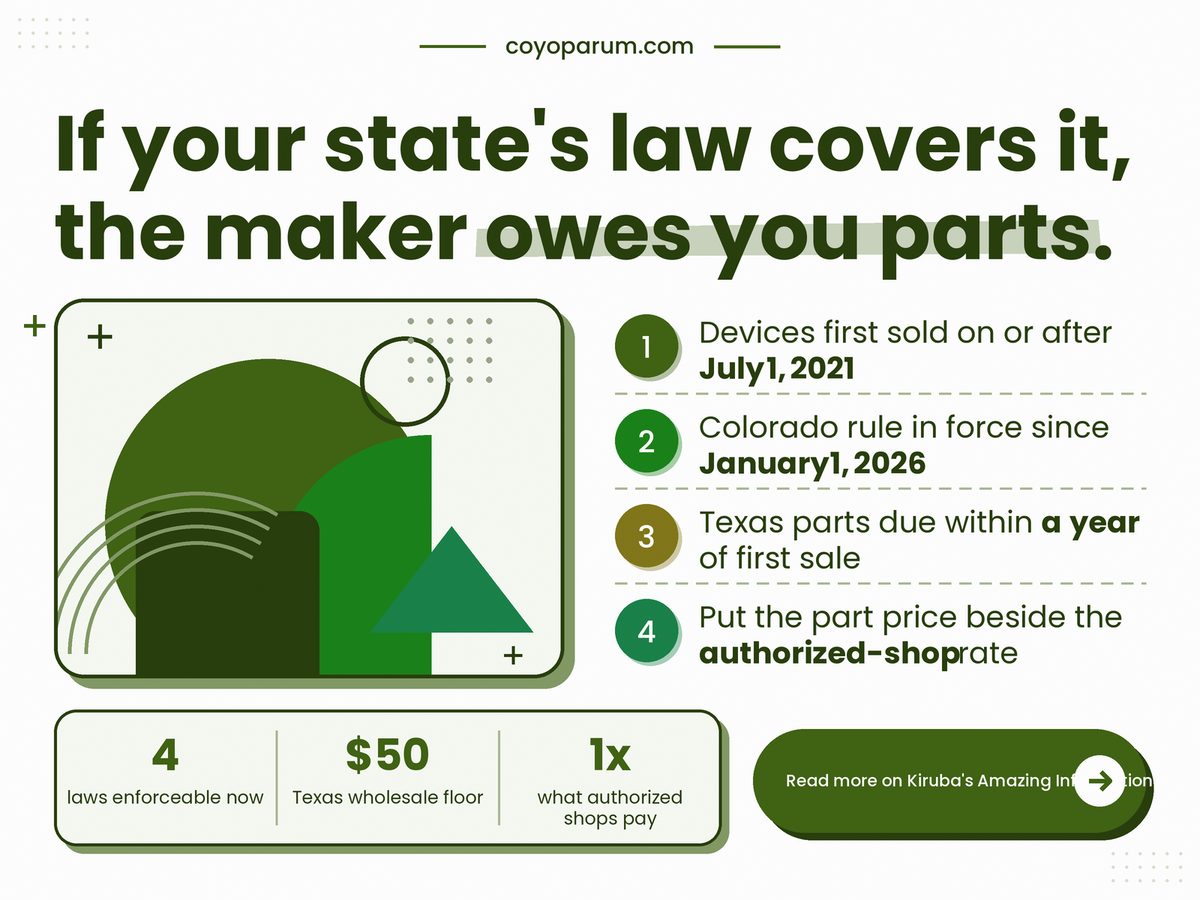
Right to repair law graphic showing covered devices, parts deadlines and key price figures

Key Takeaways (TL;DR)

Four states now require makers to supply parts or repair materials, and each law starts on its own date.

  • Colorado's rule has applied since January 1, 2026, to devices first sold on or after July 1, 2021.
  • Colorado restricts parts pairing in three specific ways, and none of them is an outright ban.
  • Massachusetts's digital bill is still pending, so no state digital repair duty is in force there yet.
  • Before you pay a shop or buy a replacement, check your state's date and your device's first-sale date.

Does Right to Repair Cover My Phone or Laptop?

Often yes, but only if the device was first sold after your state's cut-off date, and the receipt is the cheapest way to check that. Colorado and New York reach phones and laptops, while the Texas analysis does not confirm them, so check before assuming.

The cut-off runs from first sale, not from the day you bought it secondhand. Colorado's legislative summary of HB 24-1121 covers equipment first sold or used in the state on or after July 1, 2021, so a laptop first sold in 2020 falls outside the rule that took effect January 1, 2026. New York runs the same logic on an earlier clock: Proskauer's summary of its law applies it only to products first manufactured and first sold there on or after July 1, 2023. The same scope question shapes most consumer rules, and the airline refund rules after the 2025 rollback show it.

Four numbers decide most cases, and each one changes what you can ask for or what you pay. The day count and the law count are my own arithmetic. The Texas floor comes from the state's bill analysis, and the parts ceiling comes from PIRG's summary of Colorado's rule.

Days Colorado's Rule Has Run

293 days

Derived from the January 1, 2026 start

Texas Wholesale Floor

$50

Cheaper devices fall outside it

Laws Enforceable Now

4 laws

Derived count, pending bills excluded

Parts Price Ratio to Shop Price

1x

You pay what authorized shops pay

The cap only helps if you can see the shop rate, and a quote that omits it leaves the limit impossible to test. A rule that says no more than is easy to nod at and hard to check.

"

A parts price capped at the shop rate is worth nothing if you never see the quote.

Which States Have Right to Repair Laws?

Four states below have a law in force now, and each one starts on its own date, so the year you check matters as much as the state. Colorado, Connecticut, Texas and New York are enforceable today, while Massachusetts has only a pending digital bill.

StateRule and in-force dateWhat it means for you
⚖️ ColoradoParts on fair terms, from January 1, 2026Covers devices first sold after July 1, 2021
⚖️ ConnecticutRepair materials for owners, from July 1, 2026Same materials authorized shops already get
⚖️ TexasParts within a year, from September 1, 2026Cheaper devices fall outside this rule
⚖️ New YorkParts on fair terms, from July 1, 2023Only devices first sold there after that date

Find your row, check the date, and the table settles most cases in one pass. A passed date means the right applies now, and a pending bill means nothing applies yet. The Connecticut and New York dates come from PIRG and Proskauer summaries rather than the statutes, so confirm them against the bill before you rely on them.

8 of 10 states cover electronics

Eight of ten listed states cover electronics, so your first check is whether yours is one of them. Source: Morgan Lewis, June 2026, a secondary count that I did not check statute by statute.

Can a Manufacturer Refuse to Sell Me Parts?

No, a maker cannot refuse outright in the four states with a law in force, because each one requires parts or repair materials to be made available to independent shops and owners. The exact duties differ, and Texas gives makers a year from first sale.

Parts pairing ties a replacement part to the maker's own software, and it is the refusal that usually hides. Colorado bars it in three specific ways, including blocking a replacement part and showing misleading warnings about unidentified parts. It still allows pairing that records information or runs standalone biometric authentication.

Texas takes a narrower route. Its bill does not bar makers from requiring remote authorization or an internet connection before a part works, so a Texas shop may still hit that gate. My view is that this gap matters more than the headlines admit. For the India rules, which differ, read right to repair in India 2026: what a phone maker actually owes you.

  • Ask the seller in writing whether a part needs online authorization before you pay.
  • Texas gives a maker 30 days to cure after written notice, and only the attorney general can enforce the rule.

Conditions to check before you pay

  • Your device's first sale falls after your state's cut-off, which the receipt usually shows.
  • The seller will put the part price beside the authorized-shop price in writing.

Repair or replace is the decision, and parts come first. The same pattern shows up when a federal rule is vacated but other law still applies, as in what still forces a subscription company to let you quit. If your state's law reaches your device, the maker owes you parts or repair materials, so send one written request this week for the part, with its price beside the authorized-shop rate. Book the shop or buy the replacement only after that answer is in writing.

Friday, October 16, 2026

12:12 PM

California DROP: What Brokers May Keep

You asked data brokers to delete you. Weeks later the status screen reads EXEMPT for one, RECORD NOT FOUND for another and nothing for a third. Which of those is a refusal? Under California DROP, the state's single deletion portal for brokers, perhaps only the blank one, because the first two are answers the law allows.

California DROP infographic with a half-shredded folder, a padlock and a smartphone

DROP does force registered brokers to delete you, but it cannot reach companies you deal with, and some replies are lawful non-deletions.

  • Only California residents can file, and only brokers with no direct relationship to you are covered.
  • EXEMPT and RECORD NOT FOUND are lawful replies; a blank status after the first reporting window is the red flag.
  • List every email and phone number you use, because brokers match only identifiers they already hold.
  • Until independent audits begin, your own rechecks are the enforcement.

Does California DROP Actually Delete Your Data?

Yes, where a registered broker holds a matching record, DROP orders deletion, inferences included, but the broker may keep the minimum personal information needed to comply, and exempt records stay put.

The Delete Request and Opt-out Platform opened to California residents in January 2026. Brokers had to start processing requests on 1 August 2026 and must check in at least every 45 days, per CalPrivacy. Count 45 days from 1 August and you reach 15 September: my arithmetic, not an announcement, but it means a status should already be in your account.

What comes back is a status code, and the codes are the fine print. CalPrivacy's testimony to the Vermont Senate (slides as of 1 May 2026) says brokers may keep the minimum personal information needed to comply. EXEMPT means the record falls under a legal exemption, OPTED-OUT means every identifier you shared was already opted out, and RECORD NOT FOUND means nothing matched. None is a refusal.

Matching runs on hashed identifiers, and a broker downloads only the identifier types it already holds. One that knows you by phone number alone will not find you if you submitted just an email, so it will honestly answer RECORD NOT FOUND. Guides saying one email is enough are wrong: list every address and number you use.

DROP covers only data brokers, meaning businesses that sell data on people they have no direct relationship with. Your bank and the shops you buy from keep their records. Headline rules often shrink on contact: compare the vacated FTC click-to-cancel rule with what the FTC junk-fee rule actually covers.

Four figures decide how much leverage you hold, all from CalPrivacy's own pages and testimony: how long you wait, and what a stalling broker risks.

Status reporting window

45 days

Silence after this, chase

Annual broker registration fee

$6,000

Small next to daily penalties

Registration enforcement actions

Nearly a dozen

Deletion cases still untested

Penalty per undeleted request

$200 a day

Clock runs per request

The penalty matters mostly as a comparison. Charged per request and per day, it overtakes a broker's yearly registration cost in about a month of ignoring one request. That break-even is my arithmetic from two published numbers.

"

Thirty days of ignoring one request costs a broker as much as a year of registration. That is the leverage. Whether the agency will use it on deletions is still untested.

What Do Brokers Keep, Row By Row?

Brokers may keep the minimum records needed to comply and anything covered by an exemption, and companies outside DROP's scope keep everything, so the table sets each rule against your next move.

Each middle cell pits what DROP makes a broker do against what it may keep.

Dimension Must delete vs may keep What it means for you
💰 Your cost Brokers pay $6,000 a year
You see no fee listed
✅ No charge to you is listed
⏱ Status clock Brokers report within 45 days
You see updates from Aug 2026
⚠️ Blank since mid-September? Chase it
🧾 Replies Deleted data and inferences
3 replies that are not refusals
⚠️ Only a blank or stale status is a problem
🌍 Who is covered Covered brokers with no tie to you
Kept by your bank or employer
❌ Everyday accounts stay untouched
🔒 Matching Found via hashed email or phone
Missed if you left one out
⚠️ List every email and number you use
⚖️ Penalties Late deletion: $200 a day each
Audits start 1 Jan 2028
⚠️ Until then, you are the auditor
🏁 Best suited for Fits a Californian with many brokers
Skip if you live elsewhere
🏁 File once, recheck every cycle

My reading: the platform is a good lever and a poor guarantee. It is strong where a broker holds a match and silent everywhere else.

One year holds about eight 45-day cycles. 45d. 45d. 45d. 45d. 45d. 45d. 45d. 45d. One cycle. Five spare days. Up to $9,000 per ignored request, per cycle. Recheck once per cycle: about eight times a year.

The decision this settles is how often to recheck: once per cycle, about eight times a year, not once and forget. The arithmetic is derived: 365 days divided by 45, and the daily penalty over one cycle gives up to $9,000 per ignored request.

What Can Go Wrong With A Data Broker Deletion Request?

Most failures come from who you are and what you listed: outside California the platform does nothing for you, and a broker holding an identifier you never submitted will answer RECORD NOT FOUND.

Residency is the hard wall, so look to your own state's rules if you live elsewhere. Then comes the evidence gap. CalPrivacy's February 2026 product-update deck leaves sign-ups, verified-resident share, completion time and support tickets blank, and the May testimony slide does the same. So no official success rate exists; anyone quoting one is estimating. Untested rights are not new: see airline refund rules after the 2025 rollback.

CalPrivacy told Vermont senators in May 2026 about nearly a dozen actions for failing to register, with no names or amounts, which suggests deletion enforcement is untested. So I would not assume a broker fears the daily penalty (a guess, and a fair one, but still a guess). Independent audits are not required until 1 January 2028, so for two years your own checks are the audit.

  • A blank status after the first window deserves a written follow-up, not a shrug.
  • RECORD NOT FOUND on a broker that holds only your phone number means you left an identifier out.
  • EXEMPT is lawful, but ask which exemption the broker relies on.

Key takeaways to act on: which of these is true for you?

  • You live in California and your status screen is still blank.
  • A broker holding only your phone number shows RECORD NOT FOUND, and you filed with just an email.
  • The company is one you deal with directly, such as your bank, so DROP will not reach it.
  • Your last status check is over 45 days old.

Here is the decision. If you live in California, file once with every email address and phone number you use, then check the status screen every 45 days and chase any blank. Elsewhere, DROP is not for you. If your fight is a rejected health claim in India, start with this guide to pushing back.

Wednesday, October 14, 2026

9:00 AM

Health Claim Rejected? Demand the Clause

Ask the insurance desk at an Indian hospital, on the day you're admitted, what share of the bill your policy will actually pay. You won't get a number. You'll get a pre-authorisation form, a polite nod and, days later at discharge, the first real answer: a deduction sheet, or a one-line note saying health claim rejected.

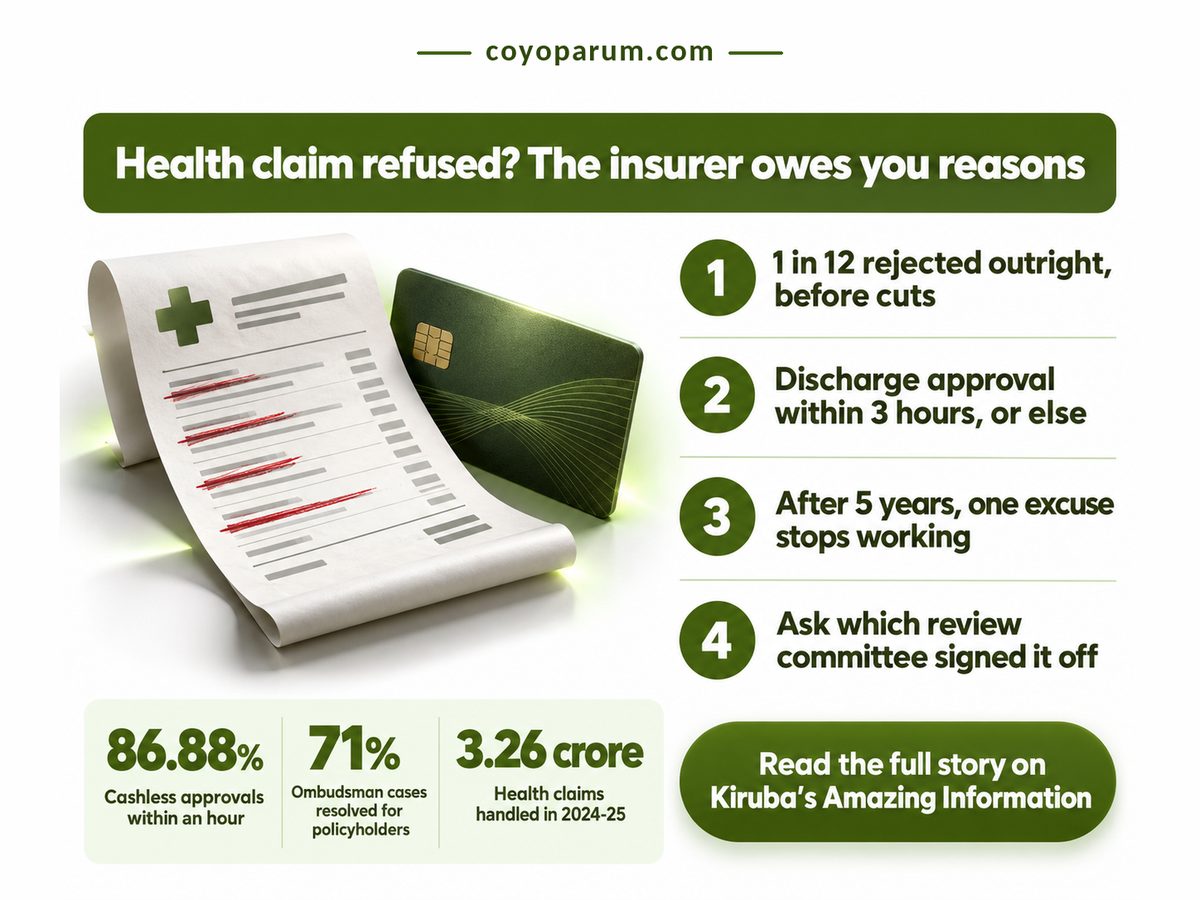
Health claim rejected infographic: hospital bill with struck lines, IRDAI deadlines and complaint stats

That up-front estimate is what policyholders keep asking for, and no rule gives it to them. What they won instead is narrower and more useful: IRDAI's Master Circular, in force since 31 July 2024, puts insurers on a clock and makes them explain every refusal in writing. The clock mostly works. The explanation is where people lose, because almost nobody demands it.

Key Takeaways

A refusal is only as strong as the clause it cites, so make the insurer name that clause and the committee that signed off.

  • Insurers must decide cashless requests within an hour and give final approval within three hours of a discharge request; delay costs beyond that are theirs.
  • A denial with no specific clause or committee approval breaks IRDAI's 2024 rules and is a complaint ground.
  • Long, unbroken cover shuts the non-disclosure excuse, so never let a policy lapse while porting.
  • Escalating is free: Bima Bharosa first, then the Insurance Ombudsman.

Why is the refusal letter your only real evidence?

Because IRDAI tracks how many health claims are refused but not why, the written reason in your own letter is the only record that can be checked against your policy wording and challenged.

Start with the scale. IRDAI's Annual Report for 2024-25, reported by Insurance Business Asia in July 2026, counts 3.26 crore health claims: 87% settled, 8% repudiated, 5% pending at year end. About one claim in 12 is refused outright, before anyone argues about partial cuts.

Now the gap. The Minister of State for Health told the Lok Sabha on 24 July 2026 that IRDAI does not collect data on why individual claims are denied, only the overall rate. Run those annual figures together and you get roughly 26 lakh refused claims in one year, none explained in any regulator table. That's my arithmetic, not IRDAI's (and it flatters the system, since a partial cut never counts as a refusal).

Here's where I part ways with the standard advice to read the policy carefully before you buy. Nobody can predict which exclusion a claims team will reach for. The better habit is the one RBI pushed onto banks, covered in our piece on what bank customers can now demand under RBI's mis-selling rules: make the seller put its reasoning on paper, then hold it there. The same logic runs through what a phone maker owes you under India's right to repair push.

Four numbers decide whether pushing back is worth your evening. The complaint figures are from the Council for Insurance Ombudsmen's 2024-25 report, via Insurance Business Asia; the waiting period is from the 29 May 2024 Master Circular, via Arthgyaan.

Moratorium on non-disclosure

60 months

After that, only fraud counts

Fee to approach the Ombudsman

Rs 0

No lawyer needed to file

Ombudsman complaints, 2024-25

53,184

You won't be a test case

Resolved for the policyholder

71%

Worth filing, never guaranteed

The moratorium is the one most people misread. Past it, an insurer cannot contest a claim for non-disclosure at purchase unless it shows fraud, and ported years count. A long-held policy refused over a hidden condition is the easiest letter to fight.

"

Seven in ten Ombudsman complaints end in the policyholder's favour, and filing costs nothing. The refusal letter opens the argument. It doesn't close it.

How long can cashless approval take at discharge?

Under IRDAI's 2024 Master Circular, an insurer has one hour to decide a cashless pre-authorisation and three hours from your discharge request to give final approval, and it bears the cost of any delay beyond that.

The surprise at discharge is rarely the wait. A Finance Ministry reply in the Lok Sabha on 1 December 2025, reported by Angel One and covering August 2024 to May 2025, shows both deadlines mostly met. What arrives late is the amount.

Category Detail What it means
🧾 Delay charges Insurer pays past 3 hours ✅ Refuse extra room-day charges
💰 Payout estimate No rule requires one ❌ You learn the amount at discharge
⏱ Cashless decision Due in 1 hour; 86.88% on time ⚠️ 1 in 8 wait longer; log the request time
⏱ Final approval Due in 3 hours; 96.69% on time ✅ The wait is rarely the real fight
⚖️ Written reasons Specific clause must be cited ✅ A vague letter is a complaint ground
⚖️ Who can deny Policy or 3-member committee ✅ Ask in writing which one signed
📊 Denial reasons Not tracked; only overall rates ❌ Your letter is the only record

Read the right-hand column alone: the clock is enforced, the money is never predicted. Contest a long wait on the bill, and a deduction you don't understand on the clause.

Insurer decision time the rules allow: 4 hours in total. 1 2 3 4 5 Admission. Pre-auth: 1 hour. Discharge ask. Note the time. Final approval. Due in 3 hours. Written reason. Clause and committee. Escalate. Bima Bharosa. Then Ombudsman.

If the insurer's two decisions together take more than four hours of your stay, the extra charges are its problem, not yours. Four hours is our own sum of the Master Circular's two deadlines, as summarised by Angel One.

Health claim rejected? Here is what still goes wrong

Even with the 2024 rules in force, three things go wrong after a refusal: no one estimates your payout in advance, cuts arrive at discharge, and the regulator cannot tell you how often a given excuse is used.

The payout estimate is the reform that would matter most, and nobody has delivered it. Insurers already hold the paperwork at pre-authorisation to tell a family what share the policy should cover, and whether a room-rent cap will trigger a proportionate deduction. That's the real test of the 2024 circular.

Escalate in order: Bima Bharosa, IRDAI's grievance portal, first, for a dated complaint number, then the Insurance Ombudsman. The same discipline works in any Indian money dispute, including fees charged on UPI payments after the August 2026 amendment. Watch your letter for these:

  • A broad heading like not medically necessary, with no clause number.
  • No committee named. Ask in writing which one approved it.
  • A non-disclosure refusal on a policy held for years. Check your continuous cover dates.
  • A gap in cover while porting. Renew first, then switch.

Act on this: tick each line against your claim

  • My refusal letter quotes a clause number I can find in my policy wording.
  • The letter names the committee that approved the denial.
  • Final approval came within three hours of my discharge request.
  • My cover has run unbroken, ported years included, past the moratorium.

The decision is simple: accept the deduction sheet, or contest it on paper. Contest it if the letter lacks a clause or a committee, if approval ran long, or if your cover is old enough to block a non-disclosure excuse. This week, write to your insurer asking which clause and which committee stand behind the cut, and file that same question on Bima Bharosa.

Wednesday, October 7, 2026

9:36 AM

Airline Refund Rules the Rollback Spared

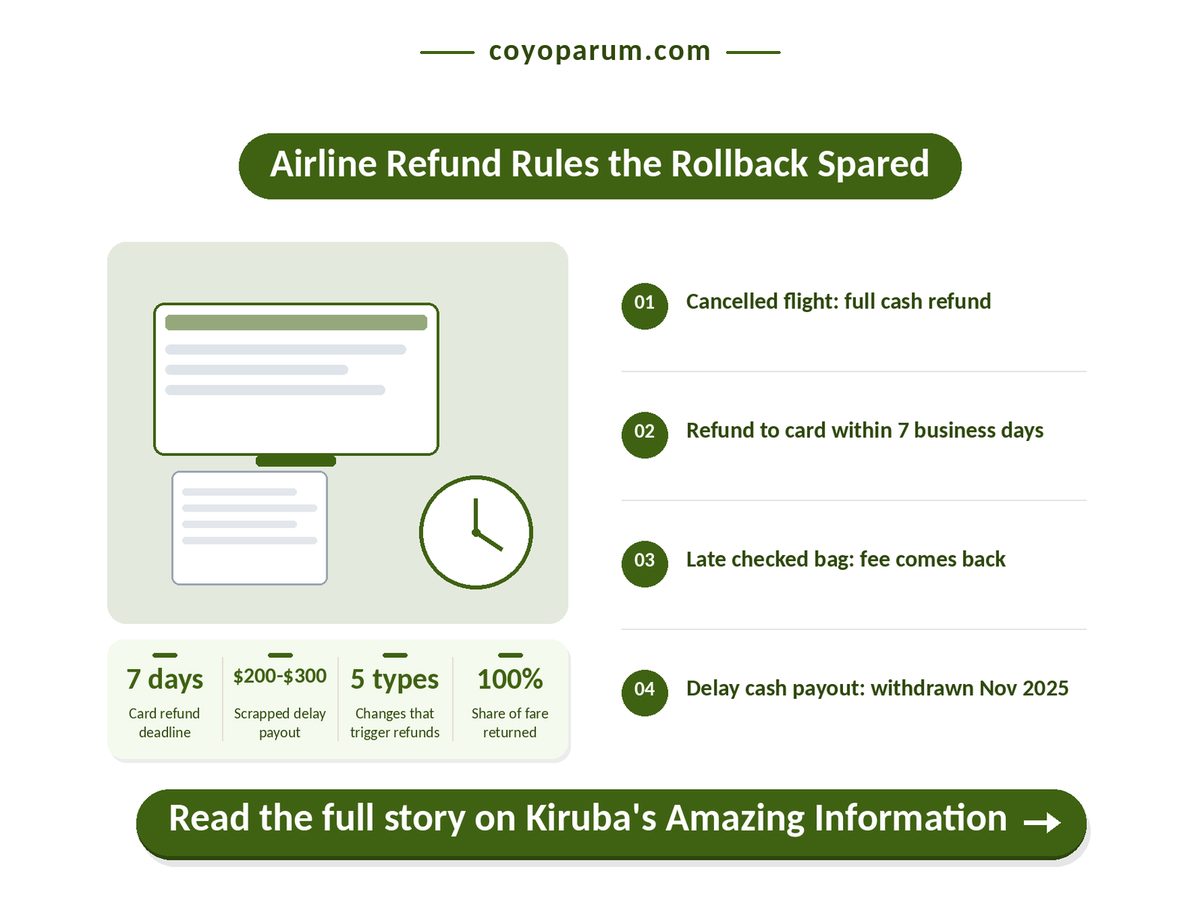
Passengers asked Washington for cash when an airline strands them for hours, the way Europe pays. In November 2025 the Department of Transportation said no and withdrew the plan. What survived is less exciting and far more useful. The airline refund rules that took effect in October 2024 still force a carrier to hand your money back, without a claim form, when it cancels or badly changes your flight and you walk away. That right was never on the table. The cash for waiting was.

Infographic on airline refund rules: 7-day card refund deadline, scrapped delay payout and four refund rights

Key Takeaways

If a US airline cancels or badly changes your flight and you decline the alternative, it owes you your money back; it owes you nothing for a delay you sit through.

  • Cash for long delays was proposed, then withdrawn by DOT in November 2025.
  • The refund goes to your original payment unless you choose a voucher, so refuse vouchers first.
  • A late checked bag or a paid extra that never worked earns that fee back, even on an on-time flight.
  • Meals and hotels depend on the airline's own pledge, not federal law.

Do airlines have to refund you if they cancel your flight?

Yes, a US airline that cancels your flight or changes it significantly must refund the full ticket to your original payment if you decline the rebooking it offers, and it must do so without you filing a claim.

DOT's final rule (89 FR 32760, April 2024) made that refund automatic from 28 October 2024. Weeks later Congress wrote it into statute through section 503 of the FAA Reauthorization Act of 2024. That second step matters more than it sounds. Much more, actually. The compensation plan was only a DOT proposal, so one notice could kill it, and one did. Undoing the refund right takes an act of Congress, which is why I would bet on it surviving the next rollback.

We have seen this pattern before. When the FTC's click-to-cancel rule was vacated, older obligations still let people quit. The useful question is the one we asked about what a phone maker actually owes you under right to repair: not what was promised, but what you can enforce.

Four numbers decide whether you leave with money or a voucher. Three come from DOT's rule as summarised by Consumers' Checkbook; the payout is the range The Points Guy reported on 14 November 2025 for the withdrawn plan. Qualifying changes: a big time shift, a different airport, an added connection, a cabin downgrade, or a less accessible connection.

Card Refund Deadline

7 business days

After that, file a complaint

Scrapped Delay Payout

$200-$300

Money you will not see

Changes That Trigger Refunds

5 types

Check yours before accepting

Share of Fare Returned

100%

Taxes and airline fees included

Treat the deadline as a diary entry, not a courtesy. It counts working days from when you turn down the alternative. Once it lapses you are not asking a favour; you are documenting a missed federal duty for DOT's complaint form.

"

Passengers asked for a few hundred dollars per long delay and were refused. What they kept matters more: the whole fare back, no form required.

None of this helps if you agree to the wrong thing at the desk.

What the airline refund rules cover, line by line

The rules cover cancelled and significantly changed flights, late checked bags and paid extras you never received, and they exclude meals, hotels, missed events and any cash for delays you sit through.

Rows run from the form your money takes down to what nobody owes you.

Category What the rule says What it means for you
🔒 Refund form Original card or cash; voucher only if you pick it ✅ Refuse credit and the cash stays yours
⏱ Refund timing Card about 9 calendar days
Other 20 calendar days
✅ Card payers wait less than half as long
⚖️ Delay trigger Domestic 3+ hours moved
Cross-border 6+ hours moved
⚠️ Time the change before accepting it
💰 Bag fee Domestic 12+ hours late
Cross-border 15-30 hours late
✅ An on-time flight can still owe you
🧾 Paid extras Wi-Fi, seat or screen paid for and not provided ✅ You get that extra's price back
🌍 Not covered Meals, hotels, missed events, delay cash: $0 by law ❌ Budget for these or insure them
🏁 Best suited for Anyone whose flight is cancelled who won't rebook 🏁 Ask for cash in writing before any voucher

The timing row is this site's arithmetic, not DOT's. A card deadline counted in working days lands around nine calendar days once a weekend falls inside it, against nearly three weeks for other payments. So for a fare that may move, paying by card gets your money back in less than half the time.

2 of 4 everyday disruptions pay you back. Owed. Flight cancelled and you refuse rebooking. Whole fare back. Owed. Paid Wi-Fi or seat never delivered. That fee back. Not owed. Hotel and meals after a cancellation. Airline's choice. Not owed. Long delay, but you still fly. No cash due.

If your problem sits in the bottom row, stop arguing federal law and read the airline's own pledge or your insurance. Sorted by this site from Consumers' Checkbook's coverage list.

Do US airlines have to compensate you for a delayed flight?

No, US airlines are not required to pay cash compensation for a delayed flight, because the Department of Transportation withdrew that proposal in November 2025 and no federal rule has replaced it.

Federal Register document 2025-20042 followed on 17 November, citing "unnecessary regulatory burdens". That is the refusal in full. Europe's EU261 pays fixed sums for long delays; the US has no equivalent, and in my view none is coming soon.

The second loss came in court. On 3 February 2026 the full Fifth Circuit vacated DOT's ancillary fee disclosure rule (Airlines for America v. DOT) over skipped notice and comment. Bag and change fees need not appear at the first fare quote, so the cheap fare on screen may not be what you pay. It is the same drip-pricing fight that played out over resort fees at hotel checkout, with the same lesson: add up the total yourself.

One area I think remains unsettled: what counts as accepting when an app rebooks you and you never reply. That is why silence is a bad strategy. Reject the change in writing.

  • A voucher you accept at the gate or in the app can stand in for the cash, so decline it first.
  • A hotel night after a cancellation depends on the airline's own pledge; screenshot it before you book a room.
  • Missed events and separate-ticket connections are your loss.

Check these four before you accept anything

  • You have not accepted any rebooking, voucher or credit yet.
  • Your new times moved past the table's delay trigger.
  • Your bag arrived outside your route's window.
  • The airline's own pledge promises a hotel, and you hold a screenshot.

The decision is not whether to complain; it is which offer to accept. Take the rebooking only if you still want to travel. Otherwise refuse it and every voucher in writing, and ask for the refund to your original payment. This week, note the refund deadline on your next trip's confirmation email so the first late day starts a complaint, not a phone queue.

Wednesday, September 30, 2026

9:30 AM

Click to Cancel Rule Died. Cancel Anyway

The request is one sentence: cancel my subscription. You joined in two taps, so you look for two taps on the way out. Instead the chat window hands you a phone number, and the agent offers a discount rather than the cancellation you asked for. Most people who push back now reach for the FTC's click to cancel rule. Wrong weapon. The rule is gone, and quoting it tells the company you stopped at the headline.

Smartphone subscription screen beside a circled bank charge, illustrating the click to cancel rule

What works is older and duller: a 2010 federal statute plus your state's auto-renewal law. Together they already forced Amazon to pay refunds. Waiting for Washington did not work.

Key Takeaways

You can still force a clean cancellation, but cite ROSCA or your state's auto-renewal law, not the FTC rule a court threw out.

  • An appeals court vacated the FTC's 2024 cancellation rule, and its replacement binds no company yet.
  • ROSCA, still in force, requires a simple way to stop recurring charges. Quote that phrase.
  • In California, a subscription bought online must be cancellable online.
  • Amazon Prime refunds arrive automatically; anyone charging a fee to release one is a scammer.

What happened to the FTC click to cancel rule?

A federal appeals court vacated the FTC's 2024 cancellation rule in full in July 2025, days before its main provisions took effect, so no federal one-click requirement binds any subscription company today.

The Eighth Circuit never said easy cancellation was a bad idea. It said the FTC skipped a required preliminary regulatory analysis, so the fix is paperwork, and paperwork is slow. In March 2026 the FTC restarted with an advance notice of proposed rulemaking, a 30-day comment call on reviving the old rule's terms. That is the bottom rung. A proposed rule and a final rule still sit above it, so nothing new binds a company this year.

The law underneath never left. The Restore Online Shoppers' Confidence Act, or ROSCA, demands clear disclosure, informed consent and "a simple mechanism to stop recurring charges." In September 2025 the FTC announced a $2.5 billion settlement with Amazon over Prime sign-ups and cancellations, including a $1 billion civil penalty, with no cancellation rule in force. A cancellation maze was illegal before the 2024 rule and stays illegal after it.

The pattern repeats: compare what the FTC's junk-fee rule on resort fees actually covers, or what a phone maker owes you under India's right to repair push. Four figures decide whether pushing back is worth an evening, three from the FTC's September 17, 2026 Prime update and one from its March 2026 notice.

Top-Up Payment Deadline

Apr 2027

Extra money, no form needed

Max Prime Payout Each

$200

Worth checking your accounts

FTC Complaints, Five Years

100,000+

Your report adds real weight

Prime Benefits Used, Now Eligible

11-20 a year

Light users now qualify too

Take the complaint count. It is the evidence file for any future rule, and a free report at reportfraud.ftc.gov joins it. A company that stalls you is betting you won't file.

"

The rule died in court. The law behind it did not, and Amazon paid for a cancellation maze while no click-to-cancel rule existed.

Can a company make you call to cancel a subscription?

Under federal law a company may offer a phone line but cannot make quitting harder than a simple mechanism, and in California a plan bought online must be cancellable online, so phone-only exits often fail.

Which law to cite depends on where you live. The table sets ROSCA beside California's automatic renewal law, the most specific version, per Barnes & Thornburg's 2025 summary. If you live elsewhere, look up your own state's auto-renewal rules first.

Dimension ROSCA vs California What it means for you
💰 Cost to use ROSCA $0, one FTC online report
California $0, one written demand
✅ Pushing back costs an evening, not cash
🌍 Who it covers ROSCA any US online sign-up
California CA users, from July 1, 2025
✅ Most readers hold at least one lever
🛠 How you quit ROSCA any simple way to stop
California same channel, 0 calls if online
✅ Joined online means you leave online
🧾 Consent ROSCA informed consent before billing
California express yes, kept 3 years
⚠️ Ask them to produce the record
📊 Reminders ROSCA none required
California every 12 months, with price
❌ Outside some states, nobody warns you
🏁 Best suited for ROSCA any US account, any state
California a California billing address
🏁 Cite your state first, ROSCA always

The shape is plain: federal law guarantees a way out, California specifies which way. My own reading of the same-channel rule, not a published figure, is that the phone calls a company can demand from a Californian who joined online number zero. Elsewhere, you argue over what "simple" means.

How do I get the Amazon Prime settlement refund?

You do not apply. The FTC's September 2026 payout update says eligible members are paid automatically, with no claim form. The cap began at $51, so a small first payment may not be your last. Lighter users qualify from October 1, and earlier recipients may get a $149 top-up if thresholds aren't met by February 2027.

56% paid. of the pool. Paid: $845M. Still owed: ~$655M. Refund pool: $1.5B.

Almost half the refund money has not gone out, so former Prime members should watch for a payment, not hunt for a claim site. Derived from the FTC's September 17, 2026 update: amount paid over the refund commitment, remainder by subtraction.

Subscription cancellation rights that still break down

Cancellation rights still break down wherever the law is vague, which mostly means endless retention offers and prepaid annual plans, and in those cases your leverage is a written record rather than a statute.

The honest grey area: nothing here settles whether a save offer you must decline twice is still a "simple mechanism." My view is one offer is fair and a loop is not (two might pass, if the second is a real price cut), but that is opinion, and the company's lawyer holds the other one.

Conventional advice says dispute the charge first. I'd reverse that: a card dispute claws back one payment but doesn't end the subscription. Cancel in writing, then dispute, the same written-demand move behind RBI's new mis-selling rules for bank customers.

  • Prepaid annual plan: cancelling stops renewal, but a refund for unused months depends on your terms.
  • A trial that turned paid without an express yes: in California, demand the money back.
  • Phone-only exit after an online sign-up: screenshot every screen.

Check these against your own account

  • You signed up online and the only exit is a phone line.
  • Your billing address is in a state with an auto-renewal statute.
  • A trial became paid and you never clearly said yes.
  • You held Prime and have seen no payment notice.

So the decision is not whether to wait for the FTC. It is which law you cite first: your state's, with ROSCA behind it. This week, pick the subscription that fought you hardest and send one written cancellation quoting ROSCA's simple-mechanism language, plus your state statute if you have one. If the answer isn't yes, file the FTC report.

Related: how California DROP deletion requests work

Sunday, September 20, 2026

10:43 PM

Resort Fees Ban: What You Still Pay

You book a room for $189 a night. The confirmation page says $189. Then you reach the final screen and there is a line you never agreed to: a resort fee, tacked on after you have already typed in your card number. That is the exact scenario the resort fees ban was written to stop, and it has been the law for well over a year now, not a proposal still stuck in committee.

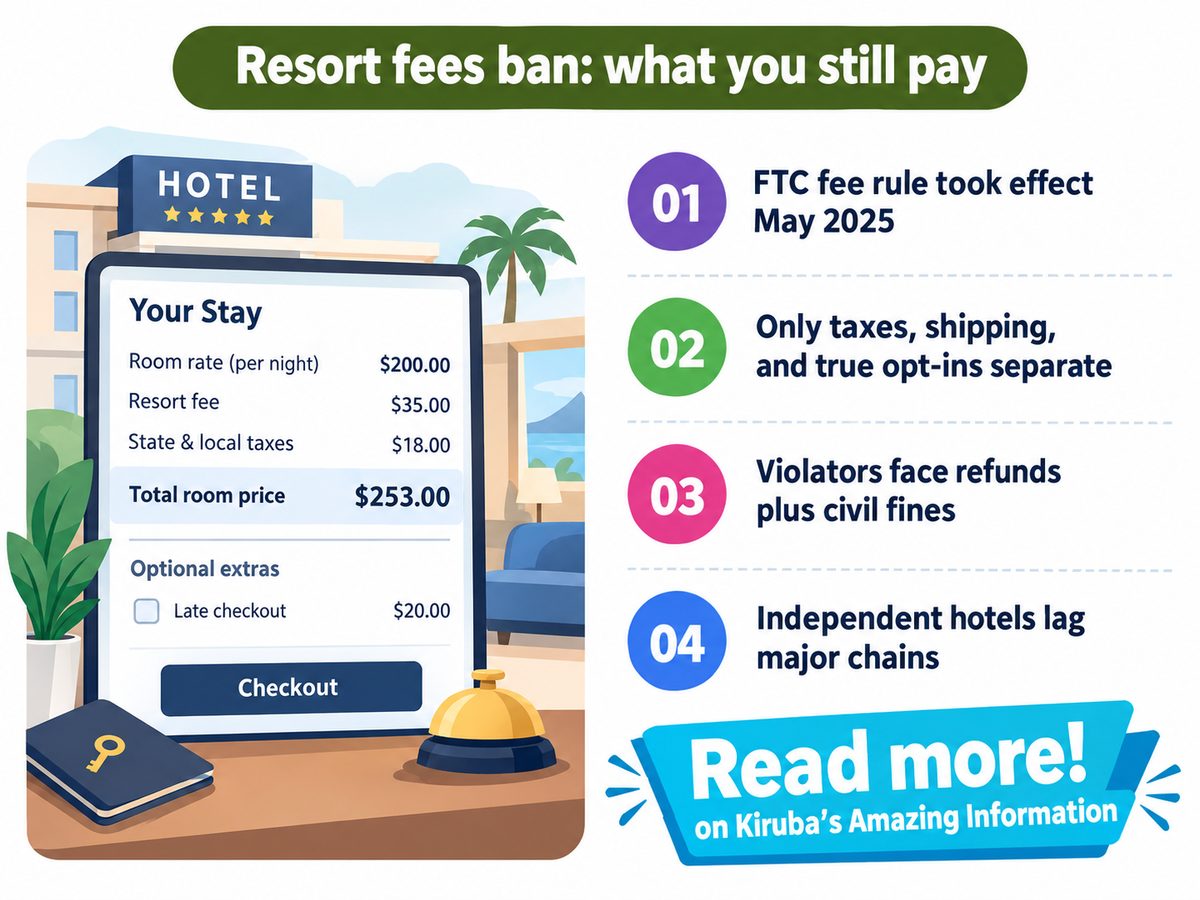
Hotel checkout screen highlighting the resort fees ban revealing the full price before payment

Ask the front desk why the price changed and you usually get a shrug, maybe a line about amenities. Push back with the actual rule and the fee often disappears right there at checkout, no manager, no argument. Assuming every extra charge is now illegal is where people get it wrong, and that mistake costs readers a winnable complaint more often than the fee itself does.

Key Takeaways: the FTC's resort fees ban makes hotels and ticket sellers show the full price up front, but three categories can still ride separately.

  • Taxes, shipping, and genuinely optional add-ons are the only charges allowed off the sticker price.
  • A resort or cleaning fee added at checkout breaks a rule with real refund and penalty teeth.
  • Independent and boutique hotels lag the big chains on compliance, so check the price twice off-brand.
  • Report a violation via ReportFraud.ftc.gov, a card chargeback, or your state attorney general.

What Does the Resort Fees Ban Actually Require?

The rule requires hotels, short-term rentals, and live-event ticket sellers to display one total price covering every fee except tax, shipping, and truly optional extras, before a shopper commits to buying.

The FTC's Rule on Unfair or Deceptive Fees took effect May 12, 2025, covering short-term lodging and live-event tickets (FTC.gov, Rule on Unfair or Deceptive Fees FAQ). Call it the junk fees rule if that is the name in the headlines; same regulation. Only three categories sit outside the advertised number: government taxes, shipping, and add-ons the buyer genuinely chooses. Resort fees, cleaning fees, and mandatory card-processing charges do not qualify; folding them in after the price is shown is the violation, not a pricing quirk.

Time the Rule's Been Live

16 months

Since May 2025, already enforceable

Projected Consumer Savings

$11 billion

FTC's decade estimate, unaudited

Sectors Covered

2

Hotel stays and live-event tickets

Chambers That Passed the Bill

1 of 2

House is done, Senate is not

That runway matters beyond press releases: the rule has outlived its first refund cycle, so attorneys general and card issuers now have precedent to cite instead of an untested regulation.

"

Eleven billion dollars is the FTC's own decade-long bet on this rule working. Whether it happens depends on inspectors, not on hotels suddenly discovering honesty.

I will push back on the common advice to just read the fine print before booking. That suited a decade of caveat-emptor pricing, not now: if the checkout price does not match the quote beyond tax and shipping, the hotel is wrong, not you. The same shift shows up in what a phone maker actually owes you just as clearly as at checkout.

The ticket side matters too. A $60 show that became $84 after service and facility charges was the textbook case behind this rule, the same push that ended blatant ticket junk fees on resale platforms. Sellers face the identical requirement hotels do: one number, shown early, that holds. India's banking regulator just told banks what customers can now demand on disclosure, the same fight over who shows the real number first.

Where Hidden Hotel Fees Still Show Up

Hidden hotel fees still show up wherever a charge gets renamed or delayed past the point a shopper already clicked buy, mostly at independent properties and rental booking flows built before the rule existed. Not every fee earns equal outrage though: some are baked in by law, some are still fair game if disclosed early.

CategoryDetailInsight
Start DateMay 12, 2025 (FTC)Already enforceable, not upcoming
Must Be UpfrontResort, cleaning, mandatory processing feesNo longer a checkout surprise
Still SeparateTaxes, shipping, true opt-in extrasLegal add-ons, not violations
Penalty2 remedies: full refund plus civil fineMore than a warning letter
Weak SpotIndependent and boutique propertiesCheck twice off the big chains
Pending BillHotel Fees Transparency Act, House-passedSenate vote still open
Report Routes4: FTC, chargeback, state AG, reviewFour ways to make it cost them
Still Fair Game3 examples: parking, ticket fees, rental surchargesFine if disclosed before you buy
Must be in the price. 3 fee types. Can stay separate. 3 categories. Resort, cleaning, processing. Tax, shipping, true opt-ins.

If a hotel or ticket seller lists a charge outside these three carve-outs, folding it into the sticker price is the rule, not a courtesy. The split comes straight from the FTC's own Rule on Unfair or Deceptive Fees FAQ, grouped here to show the divide at a glance.

Read down that table once and the pattern holds. Anything with mandatory attached to it belongs in the sticker price, anything genuinely optional does not, and the gap between those two words is where every dispute in this piece actually lives.

Can Hotels Still Charge a Cleaning Fee?

Yes, a cleaning fee is legal, but only when it is already folded into the total price shown before checkout; charged as a separate line after that point, it is exactly what the rule bans, not a gray area.

Vacation rentals are where this gets messy fastest. A host can still call something a cleaning fee and mean it honestly, a real one-time charge disclosed at the top of the listing, well, disclosed if the host actually bothered. The violation is not the fee's name, it is when it shows up. I would argue platforms carry more blame than individual hosts, since the booking flow still lets a price change after a guest has effectively committed.

This is not only a hotel story either. Payment processors have run the identical playbook for years, adding a charge only once you are deep into checkout; read what India's new payment fee rules actually change for the same disclosure fight playing out on a different rail entirely.

  • A destination fee or amenity fee that appears only after you enter payment details.
  • A quoted nightly rate on the search page that does not match the price at final checkout, beyond tax.
  • A mandatory resort fee framed as optional with no real way to decline it.
  • A ticket service fee added only after you have already selected seats.

Check your own situation before you file anything:

  • Your card statement shows a higher total than the price you were quoted at search.
  • The extra line appeared only after you had already entered payment details, not before.
  • The property is independently run, not a major chain, and its listed price has not changed since last year.

Before you book anything this week, screenshot the quoted total and compare it to what you are actually charged at checkout. If the only differences are tax, shipping, or something you chose, you are fine. If not, you are citing a specific rule with a date and a screenshot, not filing a vague complaint. That is the difference between a shrug at the front desk and a fee actually coming off the bill.

Related: what happened to the FTC's click to cancel rule

Related: airline refund rules the 2025 rollback left standing